Skip to content
ResourcesFAQContact
Hero

Advancing trust, standards and growth in India's gold loan ecosystem

  • 11.1%

    Share of India's retail credit

    TransUnion CIBIL · Apr 2026

  • ₹3.41 lakh crore

    NBFC gold loan book

    RBI sectoral data · Jun 2026

  • 69.3%

    Year-on-year growth in that book

    RBI sectoral data · Jun 2026

  • ~25,000 tonnes

    Gold held by Indian households

    Published industry estimate

Who we are

A platform for a stronger, more responsible gold loan ecosystem.

Constituted as
A collaborative, non-commercial industry forum
Membership
Gold loan NBFCs, banks and financial institutions engaged in lending against gold
Core mandate
Standards · Governance · Research · Industry representation
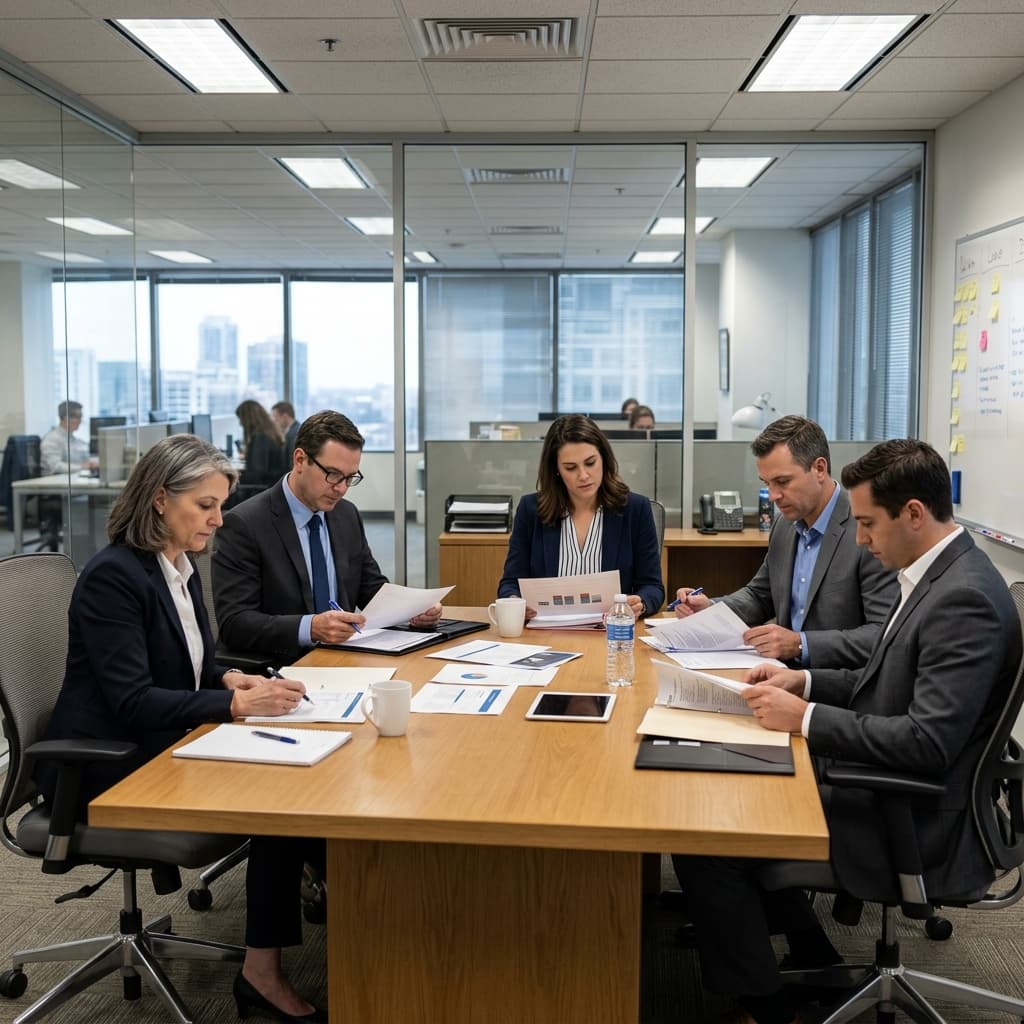
Professionals in business attire reviewing documents around a meeting table in a modern corporate office.

Why it matters

Gold-backed lending sits at the centre of India's credit access story.

  1. 01

    Households

    A significant share of household savings is held as gold.

  2. 02

    Financial inclusion

    Collateralised lending reaches borrowers underserved by unsecured credit assessment.

  3. 03

    Credit access

    Secured liquidity at a defined loan-to-value, within a common regulatory framework.

  4. 04

    MSMEs

    Working-capital continuity for small enterprises and self-employed livelihoods.

  5. 05

    Economic activity

    Consumption, production and enterprise investment across regional economies.

What we stand for

Four pillars of institutional purpose.

  1. Pillar 01

    Regulatory alignment

    Supporting responsible alignment with regulatory expectations.

  2. Pillar 02

    Ethical lending

    Promoting responsible lending practices through a shared code of conduct.

  3. Pillar 03

    Consumer protection

    Encouraging stakeholder-centric practices and clear disclosure.

  4. Pillar 04

    Industry development

    Supporting research and capability building for sustainable growth.

SRO & Governance

Governance built on transparency and accountability.

Governance framework

  1. Tier 01Representation

    General Body — member institutions

    Gold loan NBFCsBanksFinancial institutions
  2. Tier 02Direction

    Board of Directors, including independent directors

    Elected directorsIndependent directors
  3. Tier 03Oversight

    Standing committees

    StandardsEnforcementGrievance redressalResearch
  4. Tier 04Execution

    Secretariat & working groups

    Compliance officerGrievance officer

Knowledge hub

White papers and publications.

Leadership

Industry representation and independence.

  • Portrait of Thomas John Muthoot

    Thomas John Muthoot

    Chairman & Managing Director

    Muthoot Fincorp

  • Portrait of Thomas George Muthoot

    Thomas George Muthoot

    Joint Managing Director

    Muthoot Fincorp

  • Portrait of Thomas Muthoot

    Thomas Muthoot

    Joint Managing Director

    Muthoot Fincorp

  • Portrait of V.P. Nandakumar

    V.P. Nandakumar

    Chairman & Managing Director

    Manappuram Finance

Members

A collective voice for India's gold loan ecosystem.

  • Muthoot FinanceMuthoot Finance
  • Manappuram Finance
  • IIFL FinanceIIFL Finance
  • Muthoot Fincorp (Muthoot Pappachan Group)Muthoot Fincorp
  • Muthoottu Mini Financiers
  • Kosamattam Finance
  • Shriram Finance
  • Bajaj Finance
  • Muthoot FinanceMuthoot Finance
  • Manappuram Finance
  • IIFL FinanceIIFL Finance
  • Muthoot Fincorp (Muthoot Pappachan Group)Muthoot Fincorp
  • Muthoottu Mini Financiers
  • Kosamattam Finance
  • Shriram Finance
  • Bajaj Finance

Membership

Be part of a stronger gold loan ecosystem.

Membership is a commitment to shared standards. Institutions engaged in lending against gold are invited to participate in the Forum's committees and research.